Maximize 2026 Retirement: Master IRA Limits for a 15% Tax Advantage
Anúncios
Retirement planning is a journey that requires foresight, strategic decision-making, and a keen understanding of the ever-evolving financial landscape. As we look towards 2026, one of the most impactful areas for individuals to focus on is optimizing their 2026 IRA contributions. With potential adjustments to contribution limits and the ongoing benefits of tax-advantaged growth, leveraging your IRA can provide a substantial boost to your retirement nest egg, potentially yielding a 15% tax advantage or more, depending on your individual circumstances.
Understanding the nuances of IRA contributions – whether Traditional or Roth – is paramount. These accounts offer powerful incentives designed to encourage long-term savings, from tax deductions today to tax-free withdrawals in retirement. But simply contributing isn’t enough; strategic optimization is key to unlocking their full potential. This comprehensive guide will delve into what you need to know about 2026 IRA contributions, how to navigate the new limits, and actionable strategies to maximize your tax benefits and secure a more comfortable financial future.
Anúncios
The Importance of Understanding 2026 IRA Contribution Limits
Each year, the Internal Revenue Service (IRS) reviews and often adjusts contribution limits for various retirement accounts, including Individual Retirement Arrangements (IRAs). These adjustments are typically made to account for inflation and other economic factors. Staying abreast of these changes is not merely an administrative task; it’s a critical component of effective retirement planning. For 2026, anticipating these limits allows you to proactively adjust your savings strategy, ensuring you don’t miss out on valuable tax benefits.
Why are these limits so important? Because they dictate the maximum amount you can contribute to your IRA each year and, consequently, the maximum amount of tax-advantaged growth you can achieve. Exceeding these limits can lead to penalties, while under-contributing means leaving potential tax savings and future wealth on the table. By understanding the projected 2026 IRA contributions, you can:
Anúncios
- Maximize Tax Deductions: For Traditional IRAs, contributions may be tax-deductible, reducing your taxable income in the present.
- Optimize Tax-Free Growth: Both Traditional and Roth IRAs offer tax-deferred or tax-free growth, meaning your investments compound without being eroded by annual taxes.
- Plan for Catch-Up Contributions: If you’re aged 50 or over, you’re typically allowed to contribute an additional amount each year, further boosting your savings. Knowing these limits for 2026 helps you plan accordingly.
- Avoid Penalties: Staying within the contribution limits prevents you from incurring excise taxes on excess contributions.
The 15% tax advantage mentioned often refers to the potential tax bracket savings you might achieve by contributing to a Traditional IRA, or the effective tax savings on withdrawals in retirement for a Roth IRA. For instance, if you are in the 15% tax bracket and contribute $6,000 to a Traditional IRA, you could save $900 in taxes in the current year. This immediate saving, coupled with long-term tax-deferred growth, makes understanding and utilizing your 2026 IRA contributions a cornerstone of smart financial planning.
Projected 2026 IRA Contribution Limits: What to Expect
While the official 2026 IRA contribution limits won’t be released until late 2025, we can make informed projections based on historical trends and current economic indicators. Typically, the IRS adjusts these limits in increments of $500 for regular contributions and $1,000 for catch-up contributions, primarily driven by inflation as measured by the Consumer Price Index (CPI).
For context, let’s look at recent years. The standard IRA contribution limit has steadily increased. For example, if the 2025 limit is $7,000, it’s reasonable to project an increase to $7,500 for 2026, assuming a consistent inflation rate. Similarly, the catch-up contribution for those aged 50 and over, which has often been $1,000 above the standard limit, might also see an increase. If the 2025 catch-up is $8,000 (including the standard limit), it could rise to $8,500 in 2026.
It’s crucial to remember that these are projections. However, financial planners often advise clients to plan based on these educated guesses to ensure they are prepared to maximize their contributions as soon as the official numbers are released. This proactive approach ensures you have the funds available and your investment strategy aligned to fully leverage the 2026 IRA contributions.
Key Factors Influencing 2026 IRA Limits:
- Inflation: The primary driver for limit adjustments. Higher inflation typically leads to higher limits.
- Economic Growth: A robust economy might indirectly influence adjustments as the government aims to encourage savings.
- Legislative Changes: While less common for annual adjustments, new legislation could always impact retirement account rules.
We recommend staying informed through reliable financial news sources and consulting with a financial advisor as 2026 approaches. This will help you confirm the official limits and fine-tune your contribution strategy for both Traditional and Roth IRAs.
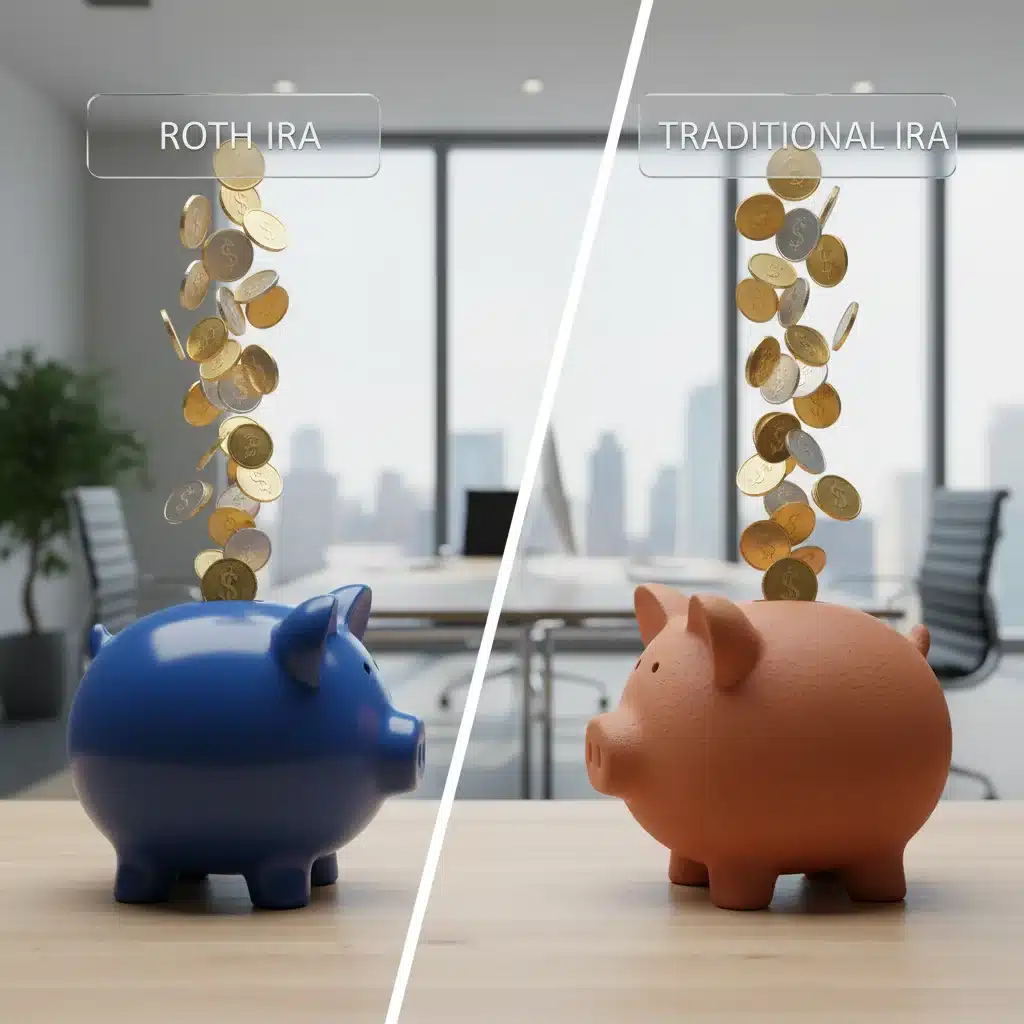
Traditional IRA vs. Roth IRA: Which is Right for Your 2026 Contributions?
Deciding between a Traditional IRA and a Roth IRA is a fundamental choice in retirement planning, and it hinges largely on your current income, anticipated future income, and tax philosophy. Both accounts allow you to make tax-advantaged 2026 IRA contributions, but the timing of the tax benefit differs significantly.
Traditional IRA: Tax Deduction Now
With a Traditional IRA, your contributions may be tax-deductible in the year they are made. This means you can reduce your taxable income today, potentially lowering your current tax bill. Your investments then grow tax-deferred, and you pay taxes on both your contributions (if deducted) and earnings when you withdraw them in retirement. This option is generally more advantageous if you expect to be in a lower tax bracket in retirement than you are now.
- Pros: Immediate tax deduction, tax-deferred growth.
- Cons: Withdrawals are taxed in retirement, Required Minimum Distributions (RMDs) begin at age 73.
- Ideal For: Those in a higher tax bracket now who anticipate being in a lower tax bracket during retirement.
Roth IRA: Tax-Free Withdrawals Later
Roth IRA contributions are made with after-tax dollars, meaning you don’t get an upfront tax deduction. However, your investments grow tax-free, and qualified withdrawals in retirement are also completely tax-free. This is particularly appealing if you expect to be in a higher tax bracket in retirement or want to ensure a stream of tax-free income in your golden years.
- Pros: Tax-free growth and withdrawals in retirement, no RMDs for the original owner, contributions can be withdrawn tax-free and penalty-free at any time.
- Cons: No upfront tax deduction, income limitations for direct contributions.
- Ideal For: Those who expect to be in a higher tax bracket in retirement, younger individuals with lower current incomes, or those who value tax-free income in retirement.
Income Limitations for 2026 IRA Contributions
It’s important to note that both Traditional and Roth IRAs have income limitations that can affect deductibility (for Traditional) or eligibility to contribute (for Roth). These limits are also adjusted annually. For Roth IRAs, if your Modified Adjusted Gross Income (MAGI) exceeds certain thresholds, your ability to contribute directly may be phased out or eliminated. For Traditional IRAs, deductibility can be limited if you or your spouse are covered by a retirement plan at work and your income exceeds certain levels.
Understanding these income thresholds for 2026 will be crucial in determining which IRA type is most beneficial or if strategies like the ‘backdoor Roth IRA’ become relevant for high-income earners. A financial advisor can help you navigate these complexities and make the best choice for your 2026 IRA contributions.
Strategies to Maximize Your 2026 IRA Contributions and Tax Advantage
Once you understand the limits and the differences between Traditional and Roth IRAs, the next step is to implement strategies that maximize your contributions and leverage the associated tax advantages. Here’s how you can optimize your 2026 IRA contributions:
1. Contribute Early and Consistently
The power of compounding is undeniable. Contributing to your IRA as early in the year as possible gives your investments more time to grow tax-deferred or tax-free. Even small, consistent contributions throughout the year can make a significant difference over time. Set up automated transfers from your checking account to your IRA to ensure you consistently meet your savings goals.
2. Front-Load Your Contributions
If you have the financial capacity, consider front-loading your contributions by contributing the maximum allowed amount at the beginning of the year. This maximizes the time your money is invested and growing. For example, if the 2026 limit is $7,500, contributing that entire amount on January 1st gives your money a full year more of potential growth compared to contributing $625 per month.
3. Utilize Catch-Up Contributions (Age 50 and Over)
If you are age 50 or older by the end of 2026, you are eligible to make additional catch-up contributions. This is a powerful tool to accelerate your retirement savings, especially if you started saving later in life or need to make up for lost time. Ensure you factor these additional amounts into your budget and contribution plan.
4. Consider the Backdoor Roth IRA Strategy
For high-income earners who exceed the income limits for direct Roth IRA contributions, the ‘backdoor Roth IRA’ strategy can be a viable option. This involves contributing non-deductible funds to a Traditional IRA and then converting those funds to a Roth IRA. While the conversion itself is a taxable event if you have pre-tax money in any Traditional IRA, if the contribution was non-deductible, the conversion of that principal amount is tax-free. This strategy allows you to effectively bypass income limitations and still benefit from tax-free Roth withdrawals in retirement. It’s crucial to understand the pro-rata rule if you have other Traditional IRA assets, so consulting a tax professional is highly recommended.
5. Rebalance Your Portfolio Regularly
While not directly related to contribution limits, regularly rebalancing your IRA portfolio ensures your investments align with your risk tolerance and financial goals. This can maximize your returns within the tax-advantaged wrapper of your IRA. Don’t just contribute; actively manage your investments.
6. Coordinate with Employer-Sponsored Plans
Your IRA contributions should be part of a broader retirement strategy that includes any employer-sponsored plans like a 401(k) or 403(b). Maximize employer matching contributions in these plans first, as that’s essentially free money. Then, prioritize fully funding your IRA up to the 2026 IRA contributions limits. If you still have funds, consider contributing more to your employer plan or other investment vehicles.
7. Stay Informed on Tax Law Changes
Tax laws can change, impacting the attractiveness of different retirement vehicles. Stay updated on potential legislative changes that could affect IRA rules, contribution limits, or tax treatment. Subscribing to financial news outlets or working with a financial advisor can help you stay ahead of these changes.
The 15% Tax Advantage: Deeper Dive into Savings
The ‘15% tax advantage’ is a general illustration of the significant tax benefits you can achieve by strategically utilizing your 2026 IRA contributions. Let’s break down how this advantage manifests:
For Traditional IRAs: Immediate Tax Savings
If you contribute to a Traditional IRA and deduct those contributions, you reduce your taxable income for the year. If you are in the 15% marginal tax bracket, every dollar you contribute (up to the limit) effectively saves you 15 cents on your current tax bill. For example, if the 2026 limit is $7,500, a full contribution could reduce your taxes by $1,125 ($7,500 * 0.15). This immediate saving can be reinvested or used for other financial goals.
For Roth IRAs: Tax-Free Growth and Withdrawals
While Roth IRAs don’t offer an upfront deduction, the long-term tax advantage can be even more substantial. Imagine contributing $7,500 annually to a Roth IRA for 30 years, earning an average annual return of 7%. Your initial contributions would total $225,000, but your account could grow to over $700,000. All of that growth – nearly half a million dollars – would be completely tax-free upon qualified withdrawal in retirement. If that $475,000 in growth were taxable at even a modest 15% rate, you’d pay over $71,000 in taxes. The Roth IRA allows you to avoid this entire tax burden, representing a massive advantage.
Tax Bracket Arbitrage
The strategic choice between Traditional and Roth IRA also involves tax bracket arbitrage. If you expect your tax bracket to be lower in retirement, a Traditional IRA’s upfront deduction is more valuable. If you expect your tax bracket to be higher in retirement (or if current rates are low and you anticipate future increases), a Roth IRA’s tax-free withdrawals are more advantageous. By making the optimal choice based on your individual circumstances, you can effectively minimize your lifetime tax burden on retirement savings, which can easily translate to a 15% or greater overall tax efficiency.
Common Pitfalls to Avoid with 2026 IRA Contributions
Even with the best intentions, individuals can make mistakes that hinder their IRA’s effectiveness. Being aware of these common pitfalls can help you navigate your 2026 IRA contributions more smoothly:
- Missing the Contribution Deadline: IRA contributions for a given tax year can typically be made up until the tax filing deadline of the following year (usually April 15th). Missing this deadline means you lose the opportunity to contribute for that specific year.
- Not Understanding Income Limitations: As discussed, income limits affect Roth IRA eligibility and Traditional IRA deductibility. Failing to account for your Modified Adjusted Gross Income (MAGI) can lead to excess contribution penalties or incorrect tax deductions.
- Over-Contributing: Contributing more than the annual limit (including catch-up contributions if applicable) results in a 6% excise tax on the excess amount for each year it remains in the account.
- Not Investing Contributions: Simply putting money into an IRA account isn’t enough; that money needs to be invested in mutual funds, ETFs, stocks, bonds, or other assets to grow. Leaving contributions as cash means missing out on potential returns.
- Ignoring the Backdoor Roth IRA Rules: If attempting a backdoor Roth, failing to understand the pro-rata rule (which taxes a portion of the conversion if you have pre-tax IRA money) can lead to unexpected tax bills.
- Failing to Rebalance: A static investment portfolio can become misaligned with your risk tolerance over time. Regular rebalancing is essential.
- Not Reviewing Beneficiary Designations: Life changes, and so should your beneficiary designations. Ensure they are up-to-date to reflect your wishes and avoid probate.
By being mindful of these potential missteps, you can ensure your 2026 IRA contributions are as effective and compliant as possible.
Conclusion: Secure Your Future with Optimized 2026 IRA Contributions
Optimizing your 2026 IRA contributions is more than just meeting a deadline; it’s a strategic move that can profoundly impact your financial security in retirement. By staying informed about projected limits, understanding the differences between Traditional and Roth IRAs, and implementing smart contribution strategies, you can unlock significant tax advantages, potentially yielding a 15% or greater benefit.
Whether you prioritize immediate tax deductions or future tax-free income, the IRA remains a cornerstone of effective retirement planning. Don’t let inertia or confusion prevent you from fully leveraging these powerful accounts. Start planning now, consult with a financial professional if needed, and make 2026 the year you take decisive steps towards a more robust and tax-efficient retirement.
Remember, the earlier you start and the more consistently you contribute, the greater the power of compounding will work in your favor. Your future self will thank you for the diligent planning and strategic utilization of your 2026 IRA contributions.